Behind on Your Books? A Catch-Up Plan Before Year-End
Behind on your books? You still have time.
If your books are behind, you can still get them current before December 31. Start by finding out where your records stop being reliable, then work forward one month at a time.
It's mid-October, and that leaves about 10 weeks. That's enough time to catch up if you take it in small, ordered steps. The goal this year is books that are accurate enough to file taxes, apply for a loan, or make a decision with.
You don't have to fix everything at once.
First, Take a Breath
Most business owners who fall behind aren't careless. They're busy. They ran jobs, met payroll, served customers, and the bookkeeping slid to the bottom of the list.
A pile of unsorted receipts and unreconciled accounts looks bigger than it is. Bookkeeping is repetitive work, and repetitive work can be broken into pieces. You don't have to fix everything at once. You have to find your starting point.
Step 1: Find Your Last Good Month
Look for the last month when everything agreed. That means the bank balance in your books matched the bank statement, and you knew why.
Open your bank and credit card accounts in your accounting software.
Check the last completed reconciliation date.
If you've never reconciled, use the last month you're confident was right. January 1 is a fine fallback.
That month is your anchor. Everything before it stays as it is. Everything after it is your catch-up window.
Step 2: Gather What You Need
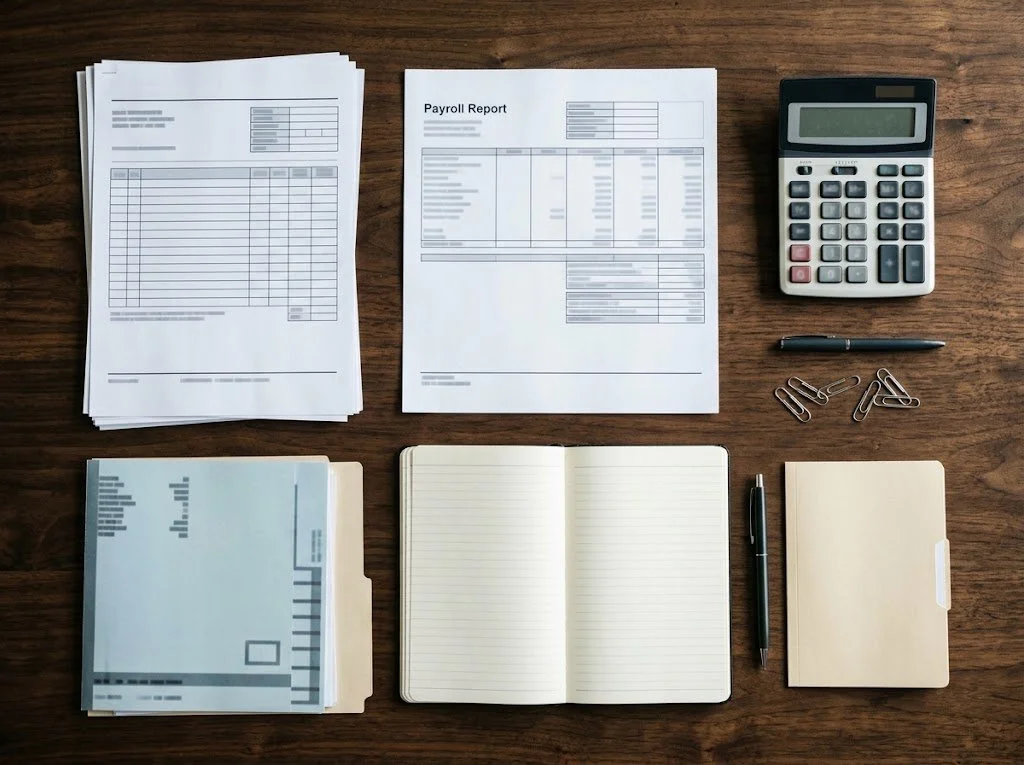
Gather statements first. Receipts only add detail.
Pull these together before you enter a single transaction:
Bank and credit card statements for every month in the window
Loan statements
Payroll reports, plus the quarterly and year-end tax filings you've already made
Sales records, invoices, and deposit reports
Receipts for larger purchases, and mileage logs if you use them
Last year's tax return
Missing statements can be downloaded from your bank. Don't let a few missing receipts stall you. Statements tell you what happened, and receipts only add detail.
Step 3: Work Forward, One Month at a Time
Resist the urge to jump around. Finish one month before starting the next.
Import or enter the bank and card transactions.
Categorize them. Mark anything you don't recognize and keep going.
Record payroll and payroll taxes.
Match deposits to invoices or sales.
Reconcile the accounts to the statement.
Glance at the profit and loss for anything odd, such as a huge repair bill or no income at all.
Each reconciled month is a checkpoint. If something goes wrong later, you know the earlier months are solid.
Step 4: Park the Mysteries
Every catch-up has a few transactions nobody can explain. Put them in a temporary "Ask My Bookkeeper" or suspense account and move on. Come back at the end with a clear head, and most of them will resolve in minutes.
Review your reports before the year closes.
Step 5: Review Before Year-End
Once you're current, run a few checks:
Profit and loss, to see if the numbers look reasonable
Balance sheet, to confirm loans, credit cards, and payroll liabilities look right
Outstanding invoices and unpaid bills
Estimated tax payments made to date
Year-end items such as contractor payments that need 1099s
This is also the time to make smart decisions before the year closes, since your numbers will finally show where you stand.
A Simple Timeline
Weeks Focus
1 Find your anchor month and gather statements
2–7 Catch up one month at a time
8–9 Clear the mystery transactions
10 Review reports, taxes, and 1099 prep
Not Sure Where to Start?
If you can't tell where your records break down, that's the most common reason people stay stuck. A short conversation can sort it out.
On a Game Plan Call, we'll look at where your books stand, decide your starting point, and map out the quickest route to being current before year-end. You'll leave knowing what to do next, whether you handle it yourself or want help.